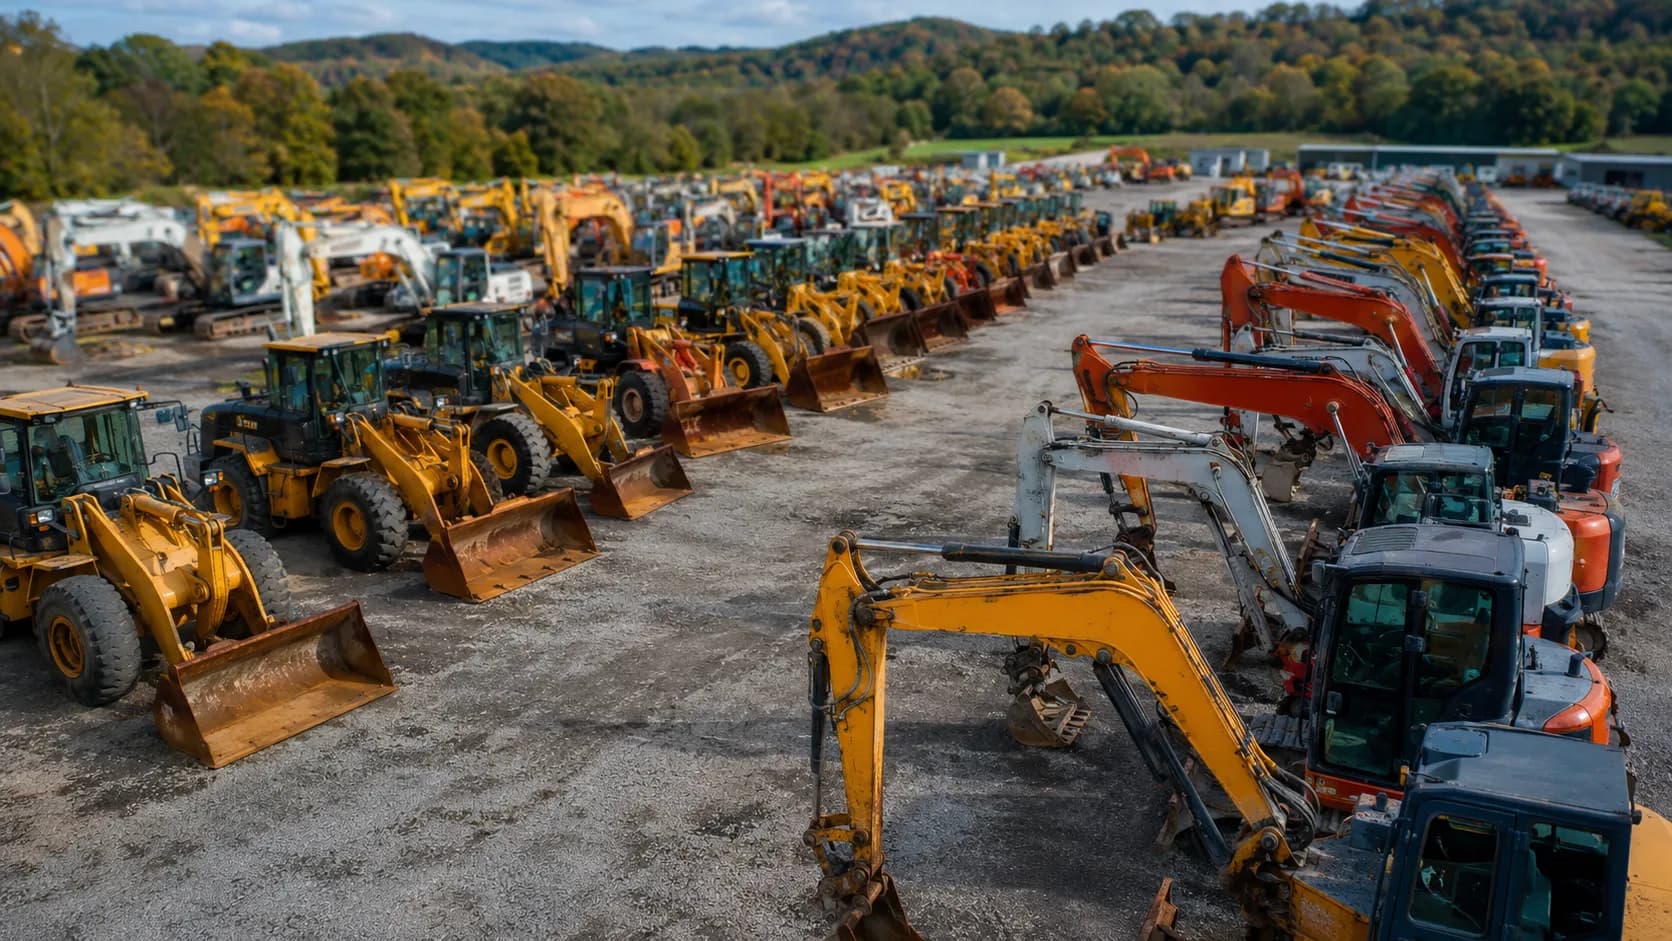
Are used equipment values going up or down? As of mid-2026, the honest answer is gently down, and flattening — a soft, normalizing market rather than a crash or a boom. Here’s what the latest auction and asking-price data shows, and what it means whether you’re buying or selling.
A dated snapshot. The figures below come from specific market reports and their dates; values vary by category and region, and the picture shifts each quarter. Pull current comps for your exact model before you act.
The story of this market isn’t the price — it’s the inventory. Fewer used machines are coming to market, and that’s what’s keeping a soft market from becoming a weak one.
The overall direction
Used values are drifting lower year-over-year by low single digits. Sandhills’ report on May 2026 data showed U.S. heavy-duty construction equipment asking values down about 3% and auction values down about 2% year-over-year, with inventory down roughly 11.5%. Ritchie Bros./Rouse similarly reported construction auction pricing essentially flat-to-slightly-down through Q3 2025. The slide is real but shallow.
By category
- Crawler excavators showed one of the larger heavy-duty declines — auction values down around 3.4% year-over-year in the May 2026 data.
- Wheel loaders saw the steepest asking-value drop (about 4% YoY) alongside sharply lower inventory.
- Skid steers and track loaders softened only modestly month-over-month.
- Dozers have held up comparatively well — a relative outperformer in recent reports, though the exact figure moves month to month.
Heavy trucks bottomed out
Used heavy trucks fell hardest in 2025 and have since turned. After steep declines early in the year, the market moved sideways by late 2025 and showed signs of stabilization into early 2026, with sleeper trucks even posting year-over-year gains. If you write off trucks based on 2025 headlines, you’re reading a market that has already turned.
What’s driving it
- New-equipment inflation is a floor. Tariffs and input costs pushed nonresidential construction input costs up about 3.2% in 2025, and OEM list prices keep climbing — which keeps buyers interested in used iron and cushions used values. (See Tariff Watch.)
- Inventory is tightening. Fewer trade-ins and machines retained in rental fleets mean less used supply — the main reason the value declines are shallow rather than steep.
- Normalization. Prices are reverting toward trend after the pandemic-era spike — ENR described used pricing as leveling off, not collapsing.
Buyer & seller takeaways
- Buyers: a favorable but narrowing window. Values are still down YoY, but tightening inventory and rising new-equipment costs mean the discount on quality, low-hour machines is shrinking — act rather than wait for a bigger drop.
- Sellers: price to current comps, not 2022 peaks. Clean, low-hour machines in tight-inventory categories (wheel loaders, excavators) still command strong interest. Our valuation guide covers the comps method.
Sources & references
- Sandhills Global — construction equipment market report, May 2026 data (published June 4, 2026)
- Ritchie Bros. / Rouse — November 2025 market trends report (Q3 2025 data)
- Sandhills / Truck Paper — used heavy-duty truck market stabilizing (Dec 2025 data, Jan 2026)
- Construction Dive — tariffs lifted nonresidential construction input costs 3.2% in 2025 (Jan 30, 2026)
- ENR — used equipment prices show signs of leveling off (2Q 2025 cost report)
Last updated .